Sustainability
The socio‑economic and environmental context has made the transition towards sustainable business models no longer postponable.
Learn more
Whitepapers
European and UK businesses are grappling with one of the most volatile operating environments in modern history.
They are coming under intense financial pressure arising from high labour and energy costs, as well as tariff wars and geopolitical tensions that are squeezing profit margins and straining supply chains. The lingering effects of the cost-of-living crisis are also rippling across the continent, with weak consumer demand providing business decision-makers with more pain.
These compounding factors are driving up corporate distress while the European Union’s (EU) business investment rate has fallen to its lowest level in more than a decade – down to 21.8% in Q4 2025 from a pre-COVID peak of 26.8% in Q4 2019.
Europe’s businesses are relied upon as engines of growth, job creation and economic resilience – yet they are facing this difficult climate with slower, more manual financial services. They consistently report a customer experience that falls far short of what’s on offer to their consumer counterparts.
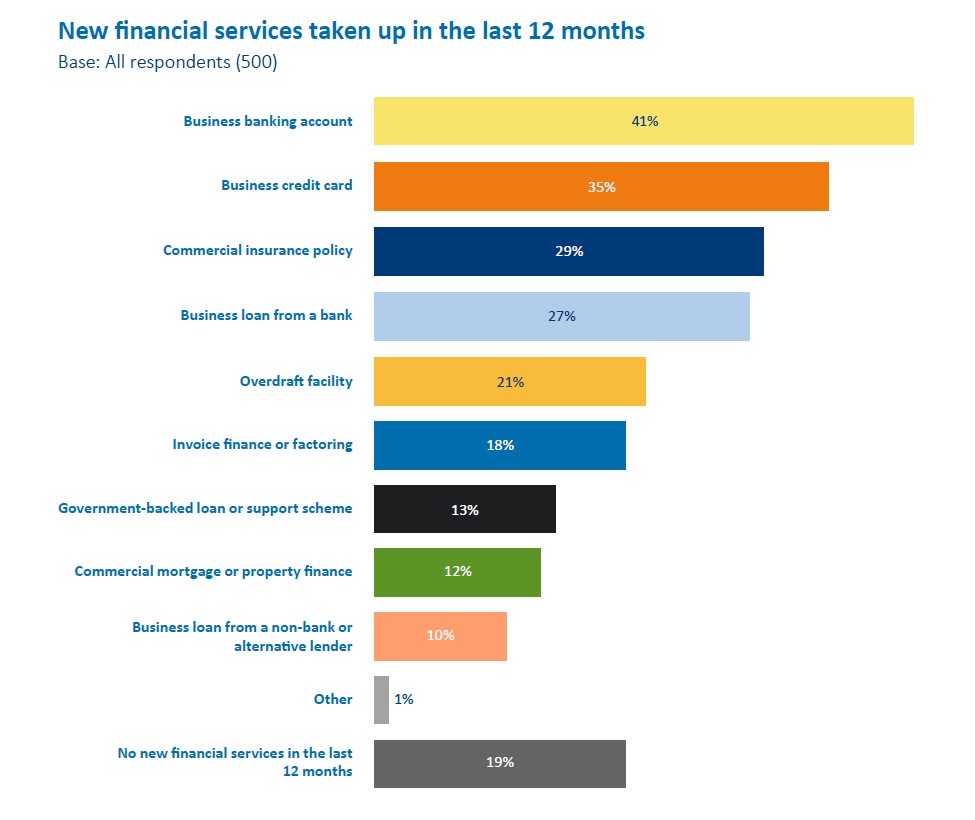
Since 2022, CRIF’s Banking on Banks series has tracked consumer sentiment when it comes to their evolving relationship with financial providers. This year, for the first time, we also surveyed 500 business decisionmakers from the UK, Ireland, Italy, Germany and Poland – alongside 5,000 consumers from these same markets – to compare their insights and explore how providers are serving both customer bases. Throughout this report we use ‘businesses’ as shorthand for decisionmakers surveyed, unless otherwise stated.
The first report, released earlier this year, looked at how consumers and businesses are experiencing today’s turbulent climate. It revealed a financial services sector under increasing scrutiny. While consumers and businesses value what’s on offer, this is coupled with a persistent sense that providers are not fully stepping up to the challenge, particularly around affordability, accessibility and fraud.
This second report drills down further into the variance between consumer and business services in areas including banking, lending and insurance, and specifically where businesses feel services are missing the mark. The gap is extensive; it spans speed and administrative burdens, access to credit and cost, the pace of innovation, business size and ultimately the extent to which providers actually understand the businesses they seek to serve.
There is now a pressing need to bring business services closer in quality to consumer services. Businesses want the speed and convenience associated with consumer style digital user experiences, and this could in turn help to facilitate economic growth in Europe.
Innovations like artificial intelligence (AI) and specifically the emergence of Generative AI (GenAI) hold considerable potential but also come with significant risks. The UK currently follows a more flexible, principles-based and sector-led approach, relying on existing regulators (such as the FCA and ICO) rather than a single AI law, while the EU AI Act adopts a risk-based approach with specific requirements and penalties for AI systems. This designation requires mandatory risk management and strict data governance, as well as effective human oversight and accountability – which is something businesses evidently want as well.
Financial institutions that can responsibly harness data and analytics to help close this experience gap – facilitating financial inclusion, tailoring business products and matching the innovations seen in consumer services – will set themselves apart and play a prominent role in fostering sustainable growth.

Download the whitepaper to explore how Europe’s financial services can better address the concerns of small and large businesses
More than 6,600 professionals are always ready to help you with CRIF solutions and services.
Contact Us